
Costs and pricing
Part of Are lead generation companies for mortgage brokers worth the cost?
Are lead generation companies for mortgage brokers worth the cost?
Compare named mortgage lead sources, real lead prices and procuration fees to see when lead generation companies earn their cost per funded case.
What to take away
- Judge lead generation companies by cost per funded case, not cost per lead.
- Typical UK procuration fees run from 0.35% to 0.5% of the loan (check your lender's current schedule), so £700 to £1,000 on a £200,000 mortgage.
- Publicly advertised lead prices sit near £10 to £40 for shared leads and £40 to £100 for exclusive or protected leads (as at 2024).
- Named routes include Unbiased, VouchedFor, Reallymoving, Lead Galaxy, Google Ads and Meta Ads.
- FCA financial promotion rules and ICO consent rules still apply to every bought lead.
- Leads are generally worth the cost only if your conversion beats the break-even rate. At £50 per lead and a £700 fee, break-even is about one funded case in 14 leads.
What a lead really costs
A mortgage lead is not one transaction. You pay for contact details, then spend adviser time on qualification, fact-find and a decision in principle (DIP).
Cost per funded case
- £250 | at 1 in 5 conversion
- £500 | at 1 in 10 conversion
- £700 | procuration fee on £200k loan
Add call attempts, compliance checks and failed identity checks. The useful figure is cost per funded case. Compare that with your procuration fee.
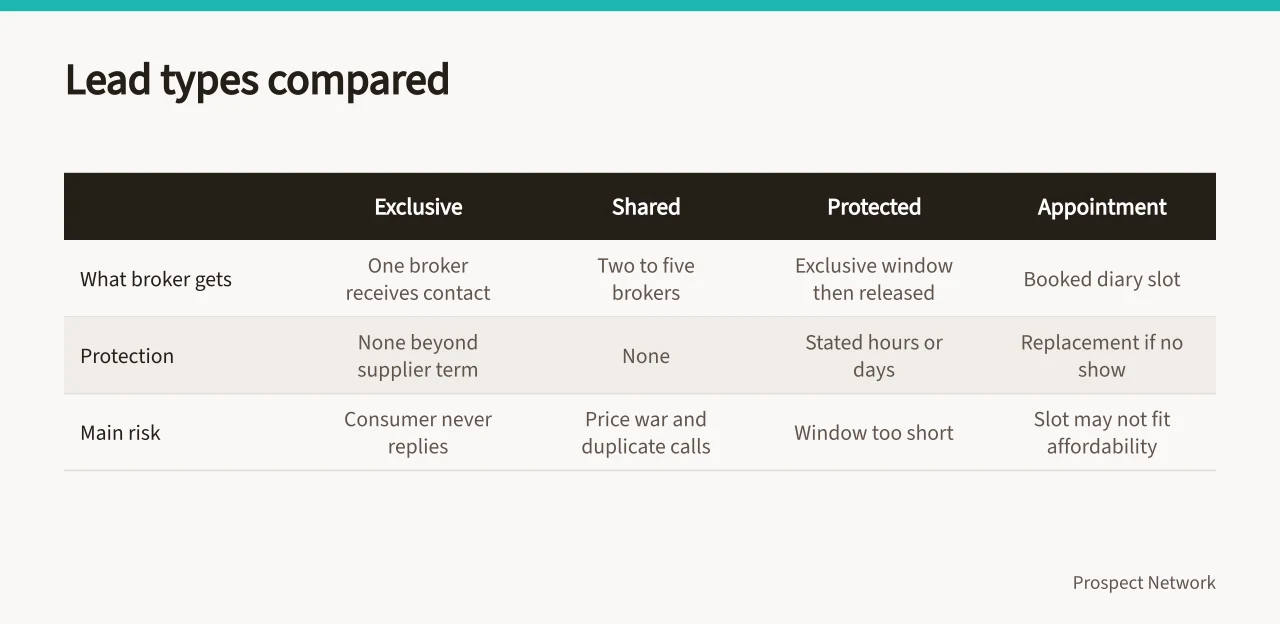
Public ranges help set expectations. Shared mortgage leads often sell for £10 to £40. Exclusive or protected leads often sell for £40 to £100. Appointment leads can reach £75 to £150. These are market ranges from publicly advertised prices as at 2024, not quotes.
Named sources and what they offer
Unbiased is a UK consumer directory for financial advice. It sells enquiries through pay-per-lead and subscription options. It suits brokers who want consumer intent. Unbiased does not publish a standard price; the fee depends on the service, postcode and lead volume.
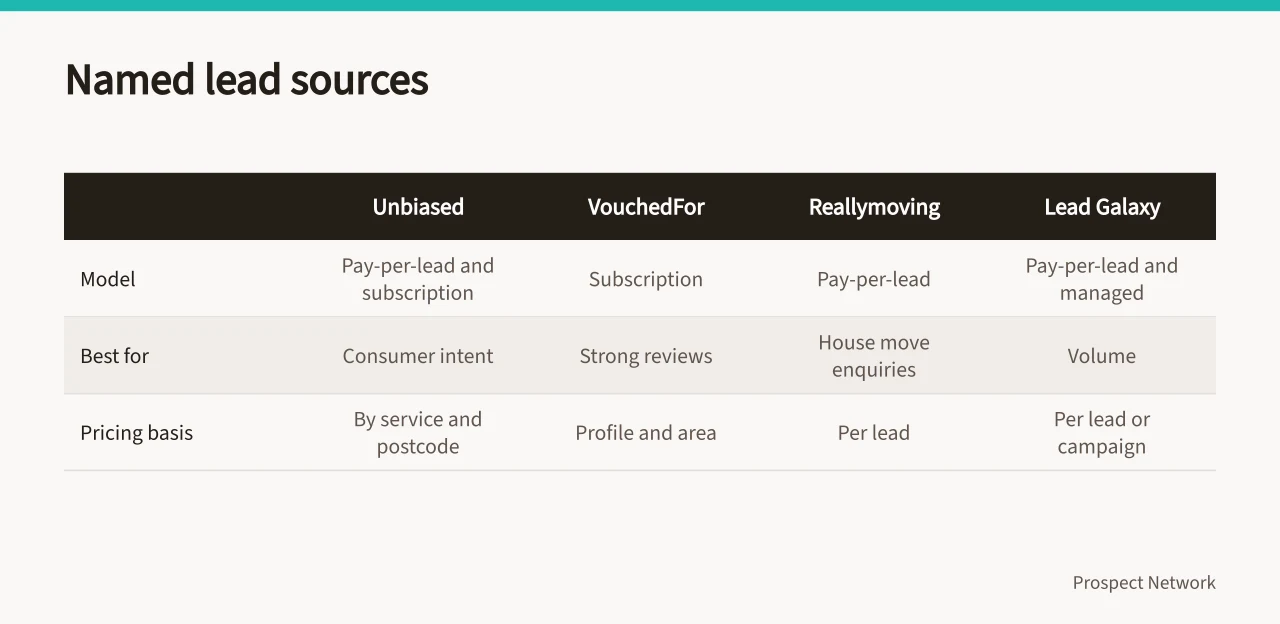
VouchedFor is a review-led directory with a subscription model for advisers. It does not sell leads per case. It suits brokers with strong client reviews and local visibility. Volume depends on profile and area. Pricing is a monthly subscription based on profile and area; it does not publish a standard rate.
Reallymoving is a home moving comparison site that sells leads to conveyancers, surveyors and mortgage brokers. It uses pay-per-lead pricing. It suits brokers who want mortgage enquiries tied to a house move. Typical mortgage lead prices depend on postcode and exclusivity; the site does not publish a fixed rate.
Lead Galaxy is a UK lead generation company in finance, property and legal markets. It sells pay-per-lead and managed campaigns. It suits brokers wanting volume. Quality varies by source, so ask for source level conversion data. Prices vary by lead type and volume; ask for a current rate card.
Google Ads lets you buy clicks on mortgage keywords. Public benchmarks for UK mortgage terms often fall between £4 and £12 per click. It suits brokers with in-house follow-up and compliance control. You own the consent and advert approval.
What the FCA expects when you buy leads
Mortgage brokers are subject to FCA rules on financial promotions. A lead supplier that sends consumers to a broker must not mislead about the service. Under the Consumer Duty, firms must show that customer outcomes are central, not just the sale.
Advertising claims about lead quality are also covered by the CAP Code, which the Advertising Standards Authority applies. Keep a dated approval record for every version of the advert you sign off.
Data protection: consent, legitimate interest and bought leads
Lead generation companies often rely on consent or legitimate interest. ICO guidance on direct marketing explains that consent must be specific and recorded. A broker needs the exact opt-in wording and the time it was given.
If you cannot see the source, you cannot assess the lawful basis. For a comparison of both routes, see legitimate interest and consent for bought leads. Ask for the consent record, not a summary.
Comparing lead types on one table
Comparing lead types
Typical cost
- Exclusive lead
- £40 to £100
- Shared lead
- £10 to £40
- Protected lead
- £40 to £100
- Appointment lead
- £75 to £150
- Referral partner
- Fee share or fixed fee, varies
What the broker gets
- Exclusive lead
- One broker receives the contact
- Shared lead
- Two to five brokers receive the same contact
- Protected lead
- Exclusive window, then released
- Appointment lead
- Consumer booked into a diary slot
- Referral partner
- Introduced by an existing professional
Protection
- Exclusive lead
- None beyond the supplier term
- Shared lead
- None
- Protected lead
- Stated hours or days
- Appointment lead
- Replacement if no show
- Referral partner
- Relationship-based
Main risk
- Exclusive lead
- Paying for a consumer who never replies
- Shared lead
- Price war and duplicate calls
- Protected lead
- Window may be too short for the consumer
- Appointment lead
- Diary slot may not fit affordability checks
- Referral partner
- Volume is hard to control
Use cost per lead benchmarks by sector only as a starting range, then replace them with your own conversion data.
Turning a quote into a cost per funded case
A quote per lead is not comparable across suppliers until you apply your own funnel. Take the monthly lead volume, the contact rate, the fact-find rate and the DIP rate. Multiply the lead price by the number of leads, then divide by the number of funded cases.
Cost per contact
- £200 | £20 lead at 10% contact rate
- £100 | £60 protected lead at 60% contact rate
A £50 lead with a 50% contact rate and a 20% conversion from contact to funded case gives a cost per funded case of £500 before adviser time. 35% procuration fee is £700, so the case is profitable. At a 10% conversion, the cost is £1,000, which is above the fee.
Break-even at a £50 lead and £700 fee is one funded case in 14 leads.
Procuration fees vary by lender and product; check your lender's current schedule for the exact rate.
Ask each supplier for a worked example using your figures, not theirs. That request separates a lead marketplace from a list seller.
A checklist before you buy
- Ask for the exact source of each lead and the date of the last permission refresh.
- Request the opt-in wording the consumer saw, with the timestamp.
- Confirm whether the lead is exclusive for a stated window, and what happens after.
- Check the replacement or credit policy for wrong numbers and duplicate records.
- Agree what happens when a consumer complains or exercises data rights.
A supplier that refuses these requests is telling you something about its record keeping.
Common questions
How much should a mortgage broker pay per lead?
There is no single market price. Compare quotes as cost per funded case, using your own conversion rate. A £50 lead that converts at one in five costs £250 per case before adviser time.
Are protected leads worth the extra cost?
They can be, when the exclusive window matches how quickly your advisers can call. A window of a few hours is worthless if your team only works office hours.
Can a broker rely on legitimate interest for bought leads?
Sometimes, but the assessment must be specific to the source and the consumer's expectation. Consent is easier to evidence when a supplier sells the same record to several brokers.
What records should a broker keep for FCA and ICO purposes?
Keep the advert, the opt-in wording, the timestamp, the lead source and every complaint. Store the replacement credits and the outcome of each case.