Rules and ethics
FCA rules for UK mortgage and insurance lead generation
FCA lead generation rules: financial promotion, appointed representative status, PERG, MCOB and ICOBS, plus Consumer Duty and claims management.
What to take away
- A pure data seller that collects contact details and passes them to an authorised firm usually needs no FCA permission.
- You need authorisation, or appointed representative status, once you advise on or arrange a regulated mortgage or insurance contract.
- PERG decides whether you are in scope; MCOB and ICOBS apply once your activity is regulated.
- Financial promotion rules and the Consumer Duty reach you through the firm buying your leads.
- Consent wording and data provenance are checked by buyers and by the ICO.
Does a lead seller need FCA authorisation?
Usually not, if you only collect and pass data. The FCA regulates the promotion, sale and administration of mortgage and insurance products, not the gathering of names and numbers.
The perimeter comes from the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001. The FCA's Perimeter Guidance manual, PERG, explains how the regulator reads it, and the PERG manual is the reference point.
A seller that asks about income and term, then passes the answers to a broker, is not arranging. One that says "this fixed rate suits you" is advising.
Financial promotion is the second test. Section 21 of the Financial Services and Markets Act 2000 restricts invitations or inducements to engage in investment activity, so a page urging consumers to "compare the cheapest life cover" needs approval from an authorised firm.
Inside or outside the perimeter?
Do you describe or recommend a product?
advising, likely inside the perimeter
collecting and passing data, usually outside
Introducers in Greater London, the South East and the North West stay outside authorisation when the contract limits them to data collection. The compliance guide for lead networks shows where that boundary breaks down.
PERG, MCOB and ICOBS: which chapters apply
PERG, MCOB and ICOBS
| Handbook | What it covers | Applies to a lead seller? |
|---|---|---|
| PERG | Perimeter guidance: PERG 2 general prohibition, PERG 4 mortgages, PERG 6 insurance | Yes, to decide whether you are in scope |
| MCOB | Mortgage promotions, advising and selling standards, product disclosure | Only if your activity is regulated mortgage business |
| ICOBS | Insurance status disclosure, product information, demands and needs | Only if you carry on insurance distribution |
Read PERG 2, PERG 4 and PERG 6 before writing scripts. They explain where introducing ends and arranging begins.
Example: compliant and non-compliant wording
Compliant and non-compliant wording
Why it fails
- "We will find you the cheapest mortgage."
- Suggests arrangement
- "Our adviser recommends this policy."
- Suggests advice
- "Enter your number for a quote."
- Fails consumer understanding
Compliant alternative
- "We will find you the cheapest mortgage."
- "We will pass your details to a regulated broker, who will contact you."
- "Our adviser recommends this policy."
- "A regulated adviser will discuss your needs with you."
- "Enter your number for a quote."
- "Enter your number and [firm] will call about life cover. Read our privacy notice."
Record for each campaign why the wording is not a financial promotion, and keep the consent text you used. The legitimate interest versus consent comparison shows which lawful basis suits bought leads and which suits your own forms.
Consumer Duty duties that reach lead sellers
The Consumer Duty requires firms to deliver good outcomes across four areas: products and services, price and value, consumer understanding, and consumer support.
Lead generation touches understanding and price and value directly. A form that takes a phone number without saying who will call fails the understanding test.
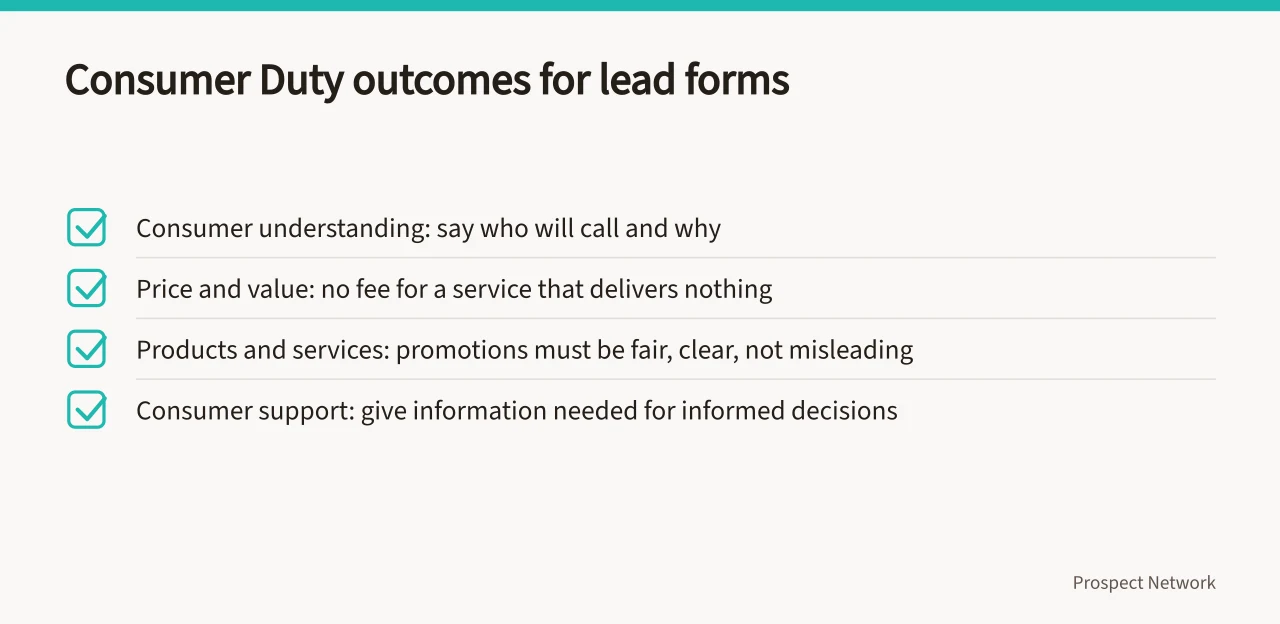
The Duty follows the distribution chain, so buyers audit suppliers. Expect questions on lead source, consent wording and complaint volumes.
Appointed representative status versus unregulated lead selling
An appointed representative carries on certain regulated activities under an authorised principal. The principal accepts responsibility, checks the representative is fit and proper, and notifies the FCA.
Own permission
- Pure data seller
- None
- Introducer
- None
- Appointed representative
- None, works under a principal
Typical activity
- Pure data seller
- Collects and sells contact data
- Introducer
- Passes leads under contract, no advice
- Appointed representative
- Discusses features, completes applications
Main risk
- Pure data seller
- Data protection and contract risk
- Introducer
- Scripts drifting into advice
- Appointed representative
- Principal liability and tighter oversight
Losing the principal means losing the ability to trade, and more of the sales process brings higher fees with more regulatory risk. Check what your agency contract needs to cover before signing.
Supervision, enforcement and data protection risk
Supervision is evidence-led. Buyers and the FCA read call recordings, landing pages and complaint logs, so keep a campaign record of audience, claims, consent wording, hand-off and complaints.
The ICO direct marketing guidance covers consent and legitimate interests for calls, texts and email.
PECR penalties now follow the UK GDPR maximum of £17.5 million or 4% of annual worldwide turnover, whichever is higher. The old £500,000 ceiling no longer applies.
Data enforcement is real: in 2021 the ICO issued a £400,000 penalty to Bounty (UK) Limited over sharing personal data without valid consent. Claims management companies sit under a separate FCA permission regime.
Common questions
Can a lead seller operate with no FCA permission at all?
Yes, if it only collects and passes data and makes no financial promotion. Advising or arranging brings it inside the perimeter.
When does appointed representative status make sense?
When you want to discuss product features or complete applications rather than pass data. It pays more per lead and puts the principal in charge of oversight.
Do lead marketplaces need their own permissions?
A marketplace passing consumer enquiries to brokers is generally outside the perimeter, but its advertising can still be a financial promotion.
Which data rules sit alongside the FCA regime?
UK GDPR and PECR. You need a lawful basis for processing and valid consent for cold calls and texts.